Financial Clarity: The New Foundation of Healthy Family Relationships
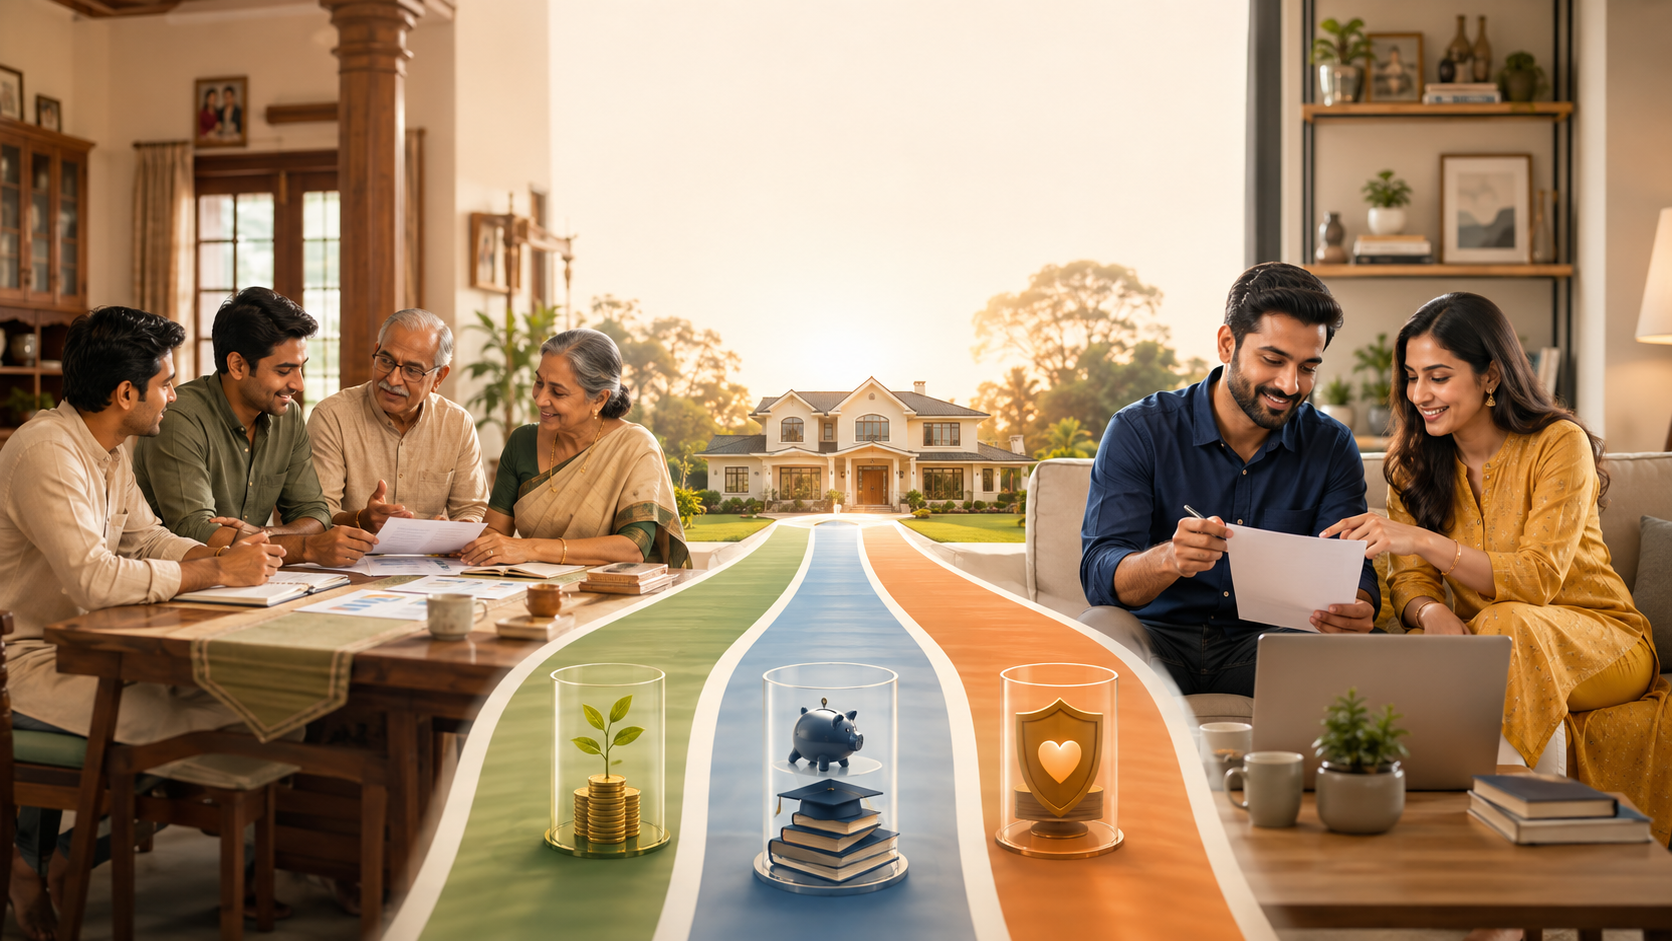
Time changes, and with every passing decade, society’s values, family structures and ways of living also evolve. Systems that worked well for one generation may not remain suitable for the next.
One such transformation can be seen in the financial relationships between family members—first between brothers in joint families and now increasingly between husbands and wives.
The Traditional Joint-Family System
In earlier generations, brothers often lived together, operated a common family business and deposited the entire family income into a common pool. Expenses, investments and major decisions were generally managed collectively or controlled by the head of the family.
This system worked reasonably well when families were large, educational and professional opportunities were limited, and individual differences in earning capacity were not substantial. Brothers who were unable to establish independent careers could join the family business and contribute according to their abilities. In return, everyone generally received an equal or collectively determined share of the family’s resources.
The system provided financial security, especially to family members who were less educated, less capable or unable to earn independently. It also protected the family business and allowed wealth to remain consolidated across generations.
However, the same arrangement became difficult to sustain as society changed.
When Contributions and Expectations Became Different
Over time, middle-class families became smaller, with parents commonly having two or three children instead of large families. At the same time, education and professional opportunities expanded.
Children within the same family began developing very different qualifications, skills, ambitions and earning capacities. Even when brothers continued in the family business, their contributions were not necessarily equal. One might be developing the business, managing major risks and working long hours, while another might be contributing considerably less.
This difference gradually started raising difficult questions:
- If contributions are different, should financial rewards always remain equal?
- Who has the authority to spend or invest money from the common pool?
- Can one brother independently use the wealth that he has helped create?
- What responsibilities does each brother have towards the parents and the extended family?
- Which assets belong to the family, and which belong to an individual member?
- How should inherited wealth be distinguished from wealth created through individual effort?
When these questions remained unanswered, resentment began accumulating.
The more capable or commercially successful brother sometimes felt that his efforts were being taken for granted. The other brother might have felt that he was being denied the equality and security traditionally promised by the joint-family system.
In many families, parents did not resolve these differences by establishing clear and fair rules. Instead, they postponed the conflict through emotional pressure, temporary compromises or intervention by relatives and society.
But postponing a disagreement does not eliminate it. Small grievances accumulate until the dispute is no longer only about money. It becomes a question of respect, recognition, authority and fairness. Eventually, brothers who once shared a home and business may stop speaking to each other, separate their families or become involved in prolonged legal disputes.
Several prominent Indian business families have also experienced publicly reported disagreements relating to ownership, management and succession. Such cases demonstrate that financial ambiguity can damage relationships regardless of the size of the family’s wealth.
How Some Families Successfully Adapted
With experience, many parents began recognizing the need for a more practical system.
They started clearly distinguishing between:
- inherited family assets;
- wealth created by the parents;
- income earned individually by their children;
- ownership and management rights in the family business;
- financial obligations towards parents; and
- responsibilities towards other dependent family members.
Instead of controlling every financial decision, parents gave their adult children sufficient freedom to build their own careers, businesses and wealth.
Initially, some parents may have felt that granting such independence meant losing authority over their children. Over time, however, many discovered the beauty of greater clarity. When financial expectations were clearly defined, parents and children could enjoy their relationships without repeatedly negotiating control over money.
Today, many financially aware parents retain ownership and control over the assets they have created during their lifetime. They provide their children with education, guidance and reasonable support but also encourage them to establish their own professions, businesses and investments.
This approach allows parents to remain financially secure while enabling their children to become responsible and independent. More importantly, it helps the family enjoy relationships without money continuously operating as the hidden source of conflict.
The Same Transition Is Now Occurring Within Marriage
Society is now witnessing a similar transformation in the financial relationship between husbands and wives.
Earlier, in many households, the wife was financially dependent on her husband. The division of responsibilities was comparatively clear: the wife primarily looked after the children and household, while the husband earned income and managed the family’s financial affairs.
Both partners generally shared the benefits of each other’s contributions. The wife’s unpaid work supported the home and family, while the husband’s income provided financial security. Since their areas of responsibility were largely separate, there was often less day-to-day interference in each other’s decisions.
This traditional arrangement was not necessarily equal in authority, and it could leave women financially vulnerable. Nevertheless, the roles and expectations were usually understood.
Today, women are educated, professionally qualified and financially aware. They can understand the family’s income, assets, liabilities and investments. Many women also earn independently, operate businesses and participate actively in financial decisions.
At the same time, husbands increasingly expect their wives to remain professionally or commercially active. A modern household may therefore have two educated, financially capable and earning partners.
This is a positive development. However, the financial understanding within marriage has often failed to evolve at the same pace.
When Equality Exists but Financial Rules Do Not
Both partners may earn, save and contribute to the family, but there may be no clarity regarding:
- ownership of their respective earnings;
- contributions towards household expenses;
- responsibility for children;
- ownership of assets purchased after marriage;
- authority over savings and investments;
- individual spending freedom;
- disclosure of loans and liabilities; and
- long-term financial security for both partners.
Neither partner may want to explain every personal financial decision, yet neither may feel comfortable allowing the other complete independence. One partner’s interference may invite an equally controlling response from the other.
Slowly, ordinary disagreements about expenditure or investment become struggles over authority, privacy, equality and trust.
A husband may feel that his financial decisions are being unnecessarily questioned. A wife may feel that her contribution is expected but her right to participate in important decisions is not recognized. If one partner temporarily leaves employment to manage children or the household, that person may become financially dependent despite having made a substantial non-financial contribution to the family.
Income can be measured through a bank statement, but household management, childcare, caregiving and career sacrifices also carry significant economic and emotional value. A fair system must recognize both paid and unpaid contributions.
Without such recognition and clarity, couples may continue living together but stop enjoying their togetherness. Money then becomes a source of control, retaliation and resentment instead of being a tool for achieving shared goals.
The Solution Is a Financial Partnership
The solution is neither complete financial separation nor unquestioned control by one partner. A healthy marriage requires a transparent, fair and mutually accepted financial arrangement.
Every couple should discuss and decide:
1. Individual Ownership
Both partners should understand which income, savings, investments and assets will remain individually owned. Each partner should ordinarily have some money that can be spent or invested independently without seeking permission for every transaction.
2. Joint Responsibilities
The couple should determine how household expenses, children’s education, healthcare, insurance and other common responsibilities will be funded.
The contribution need not always be equal in amount. It should be fair after considering the income, time, domestic work and caregiving responsibilities of both partners.
3. Joint Savings and Investments
The couple should identify their shared financial goals, such as purchasing a home, educating their children, building an emergency fund or planning for retirement.
A suitable portion of their income can be regularly invested towards these joint objectives.
4. Recognition of Unpaid Work
If one partner reduces working hours or leaves employment to care for children, parents or the household, that contribution should not be treated as financially worthless.
The couple should ensure that the non-earning or temporarily non-earning partner continues to have access to money, insurance, investments and long-term financial security.
5. Financial Transparency
Both partners should disclose material assets, loans, guarantees, insurance policies and major financial commitments. Transparency is especially important where a decision can affect the security of the entire family.
However, transparency should not become continuous surveillance. Knowing the family’s overall financial position is different from demanding an explanation for every small personal expense.
6. Decision-Making Limits
Couples can decide a reasonable financial limit up to which either partner may spend or invest independently. Transactions above that limit, or decisions involving loans, guarantees, property or substantial family savings, may require mutual discussion.
7. Protection Against Uncertainty
Both partners should be financially protected against illness, death, disability, loss of employment or career interruption. Suitable insurance, emergency savings, nominations, wills and access to essential financial information can prevent future hardship.
Clarity Does Not Weaken Relationships
Financial independence does not mean secrecy, and transparency does not mean control.
Similarly, defining financial boundaries does not weaken a marriage or family. It prevents unspoken expectations from gradually turning into resentment.
A relationship becomes stronger when people stay together because of affection, trust and companionship—not because financial dependence leaves them with no meaningful choice.
The lessons learned from conflicts between brothers are equally relevant to modern marriages. Whenever contributions, ownership, responsibilities and decision-making rights remain undefined, even loving relationships can deteriorate.
Families cannot continue applying rules created for an earlier social structure when education, earning capacity, gender roles and individual aspirations have fundamentally changed.
From a Common Pool to a Common Purpose
The traditional family system was often built around a common financial pool. The modern family may need to be built around a common purpose instead.
A common purpose does not require every rupee to be jointly owned. It requires both partners to agree on what they are building together while respecting each other’s individual identity and contribution.
The ideal financial arrangement may therefore include:
- some individually owned income and assets;
- some jointly managed household funds;
- some investments for shared goals;
- clearly allocated responsibilities; and
- complete transparency regarding decisions that materially affect the family.
There is no single formula suitable for every family. The right arrangement will depend on the couple’s income, responsibilities, values and life circumstances. What matters is that the arrangement is consciously discussed and mutually accepted rather than silently assumed.
Conclusion
Every generation must redesign family relationships according to its social and economic realities.
The joint-family model once provided security but created conflict when individual contributions and aspirations changed. Families that introduced clear boundaries regarding ownership, responsibility and authority were better able to preserve their relationships.
Marriage is now passing through the same transition.
As husbands and wives increasingly become equal educational, professional and financial partners, their financial arrangements must also evolve. Both partners need independence, but they also need transparency. Both need individual space, but they must remain accountable for shared responsibilities. Both financial earnings and unpaid family contributions must receive appropriate recognition.
Clear financial boundaries are not walls between family members. They are guidelines that prevent misunderstanding and allow relationships to breathe.
When ownership, responsibilities and decision-making rights are fair and transparent, families can stop fighting over the common pool and begin working towards a common purpose. That is when money supports companionship instead of controlling it—and family members can truly enjoy the beauty of being together.